

Buying a detached home as a first-time buyer in Ontario is harder than buying a condo, but it is not out of reach, and the rules have shifted in buyers’ favour since late 2024. Insured mortgages now go up to $1.5 million, first-time buyers can stretch payments over 30 years, and tax-sheltered accounts can build a serious down payment. Here is how each piece works, with real numbers you can plug into your own plan.
TL;DR
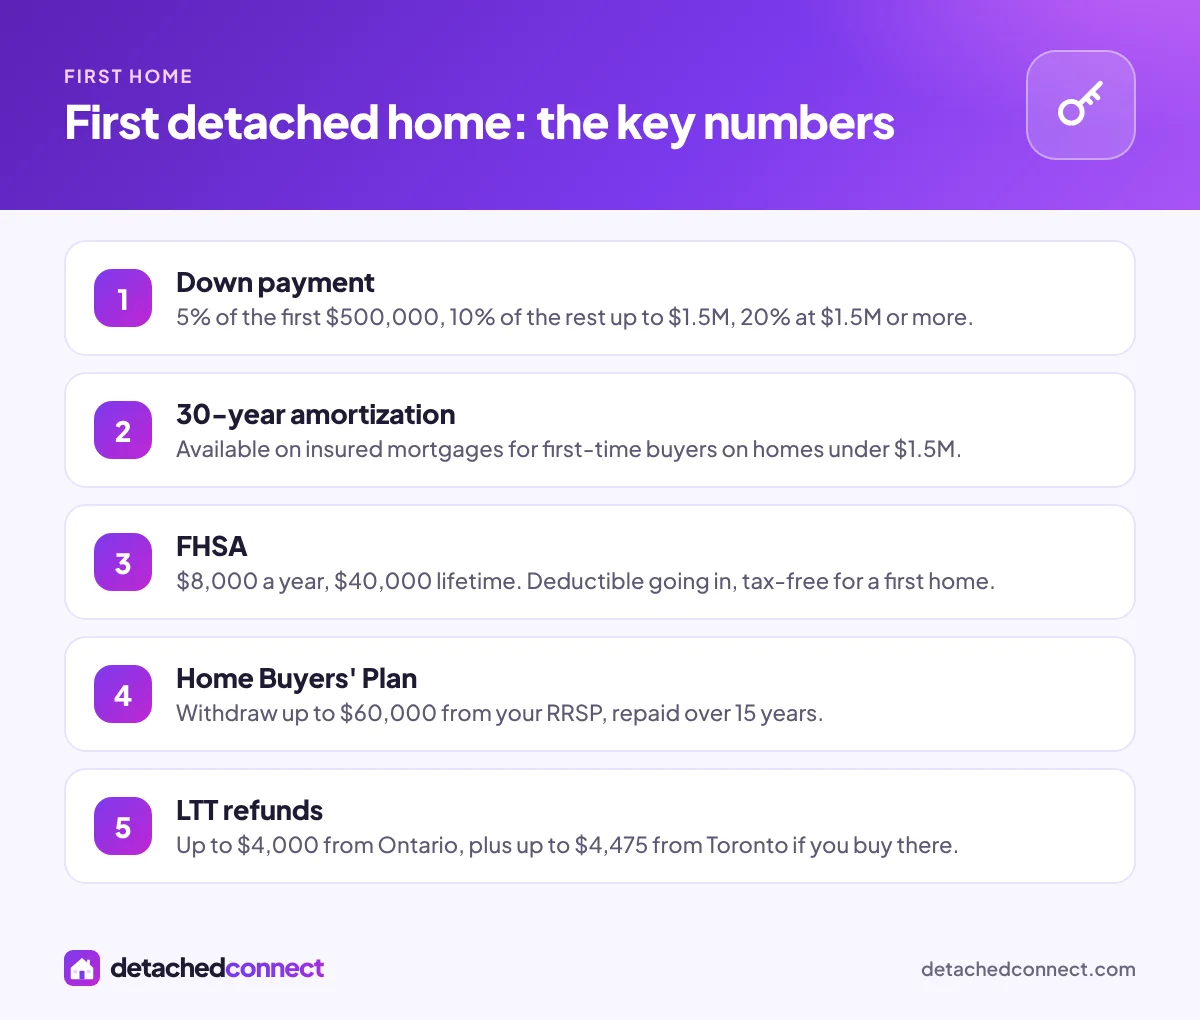
- Minimum down payment is 5% of the first $500,000 and 10% of the portion up to $1.5 million. At $1.5 million or more you need 20%.
- First-time buyers with an insured mortgage can choose a 30-year amortization on homes priced under $1.5 million.
- An FHSA ($8,000 a year, $40,000 lifetime) and the RRSP Home Buyers’ Plan (up to $60,000) can be used together for the same home.
- Ontario refunds up to $4,000 of land transfer tax for first-time buyers, and Toronto rebates up to $4,475 more.
How much down payment a detached home needs
Federal rules set the minimum down payment on a sliding scale. Below 20% down, your mortgage must be insured, and that insurance is only available on homes priced under $1.5 million.
| Purchase price | Minimum down payment | How it is calculated |
|---|---|---|
| $700,000 | $45,000 | 5% of $500,000 + 10% of $200,000 |
| $900,000 | $65,000 | 5% of $500,000 + 10% of $400,000 |
| $1,100,000 | $85,000 | 5% of $500,000 + 10% of $600,000 |
| $1,500,000 | $300,000 | 20% of the full price |
The $1.5 million line
Notice the jump at the top of the table. A home at $1,499,000 needs about $124,900 down, while a home at $1.5 million needs $300,000, because insurance is no longer available. If you are shopping detached homes near that price, set your search ceiling just under it unless you have the full 20%.
Mortgage default insurance and the 8% tax
With less than 20% down, you pay a one-time insurance premium that is added to your mortgage. Using CMHC’s published rates, the premium is 4.00% of the loan when you put down between 5% and 9.99%, 3.10% between 10% and 14.99%, and 2.80% between 15% and 19.99%. In Ontario, provincial sales tax of 8% applies to the premium, and it cannot be added to the loan, so it comes out of your pocket at closing.
Example: on a $900,000 detached home with $65,000 down, the mortgage is $835,000. A 4.00% premium is $33,400 on a 25-year amortization, and the 8% tax on it is $2,672 in cash on closing day.
Qualifying: 30-year amortization and the stress test
Down payment gets you in the door. Qualifying for the mortgage decides how much house you can carry.
30-year amortization for first-time buyers
Since December 15, 2024, an insured mortgage can use a 30-year amortization if at least one borrower is a first-time buyer and the home, resale or new, is priced under $1.5 million. Spreading payments over 30 years instead of 25 lowers the monthly payment and can raise the amount you qualify for, but you pay more interest over time. CMHC charges 0.20 percentage points more on the premium for the longer amortization, so the 4.00% example above becomes 4.20%, or $35,070, with $2,805.60 in tax.
The stress test
Lenders must check that you could still afford payments at a higher rate: the greater of your contract rate plus 2 percentage points, or 5.25%. For insured mortgages, CMHC also caps housing costs at 39% of gross income and total debt payments at 44%. Car loans and credit card balances count against that second number, so paying them down before you apply can make a real difference.
Tax-sheltered savings: FHSA and the Home Buyers’ Plan
Both programs use the same basic first-time buyer test: you have not lived in a home that you or your spouse or common-law partner owned in the current year or the previous four calendar years.
First Home Savings Account (FHSA)
You can contribute $8,000 a year, up to $40,000 in total, and carry forward up to $8,000 of unused room into the next year. Contributions are generally tax-deductible, and a qualifying withdrawal for your first home is tax-free. The account can stay open until the end of the year of its 15th anniversary, the year you turn 71, or the year after your first qualifying withdrawal, whichever comes first. The CRA’s FHSA page has the full rules.
RRSP Home Buyers’ Plan (HBP)
The HBP lets you withdraw up to $60,000 from your RRSPs to buy a qualifying home, then repay it over 15 years. For first withdrawals made from January 1, 2026 to December 31, 2028, repayments start in the fifth year after the withdrawal, so a 2026 withdrawal is first repaid in 2031. Details are on the CRA’s Home Buyers’ Plan page.
Stacking them
The CRA confirms you can make HBP withdrawals and a qualifying FHSA withdrawal for the same home. A couple who both qualify could each bring up to $40,000 in FHSA contributions plus up to $60,000 from the HBP, before any investment growth in the FHSA. That is often what makes a detached down payment possible.
Tip: Open your FHSA as soon as you think you might buy, even with a small deposit. Contribution room only starts building in the year you open the account, so every year you wait is $8,000 of room you never get.
Run your own numbers
Try different prices, down payments and amortizations to see your payment and land transfer tax before you start viewing homes.
Land transfer tax refunds and other first-time breaks
Land transfer tax is one of the biggest closing costs on a detached home, and first-time buyers get some of it back.
Ontario and Toronto refunds
Ontario refunds up to $4,000, which means no provincial tax on the first $368,000 of the price. You must be at least 18, a Canadian citizen or permanent resident, never have owned a home anywhere in the world (the same applies to your spouse while you were together), and live in the home within nine months. Your lawyer usually claims it at registration; otherwise you have 18 months to apply. See the province’s first-time homebuyer refund rules. Buying in Toronto adds the municipal tax, with a first-time purchaser rebate of up to $4,475.
Example at $900,000: outside Toronto, Ontario tax is $14,475, or $10,475 after the refund. In Toronto, you pay the provincial and municipal tax, $28,950 together, or $20,475 after both rebates.
Other help worth knowing
- Home buyers’ amount: a non-refundable federal tax credit you can claim on up to $10,000 in the year you buy.
- New-build detached homes: the federal First-Time Home Buyers’ GST/HST rebate is worth up to $50,000 on new homes up to $1 million and phases out by $1.5 million, for agreements signed with a builder on or after March 20, 2025. Ontario has also introduced temporary HST relief on new homes, and those rules have changed several times, so ask your lawyer exactly what applies to your agreement.
These figures were checked in October 2026, but programs change. Confirm the details with your lender, lawyer and accountant before you rely on them.
A realistic plan to get into a detached home
- Get pre-approved early so you know your real ceiling under the stress test, at both 25 and 30 years.
- Open an FHSA now, and decide with an accountant whether the HBP makes sense on top of it.
- Set aside cash for closing costs, the 8% tax on any insurance premium, and an inspection.
- Widen the search: a bungalow, a 1½-storey or a different city can change what is possible. Our guide to detached house styles helps you compare, and you can browse detached homes by city.
- Read our five costly buyer mistakes before you write an offer.
If a detached home still feels a stretch, our comparison of detached, semi and townhouse homes shows what you give up and what you keep with each step down.
Key takeaways
- Under $1.5 million, you can buy with as little as 5% on the first $500,000 and 10% on the rest.
- The 30-year option lowers payments for first-time buyers but adds 0.20 points to the insurance premium and more interest over time.
- Budget cash for the 8% Ontario tax on any default insurance premium.
- Use an FHSA and the Home Buyers’ Plan together for the largest tax-sheltered down payment.
- Claim the Ontario refund of up to $4,000, plus Toronto’s rebate of up to $4,475 if you buy there.
Frequently asked questions
What is the minimum down payment on a $1 million detached home in Ontario?
It is $75,000: 5% of the first $500,000 ($25,000) plus 10% of the remaining $500,000 ($50,000). You will also need mortgage default insurance.
Can first-time buyers get a 30-year mortgage in Ontario?
Yes. Since December 15, 2024, first-time buyers with an insured mortgage can choose a 30-year amortization on homes priced under $1.5 million, with a slightly higher insurance premium.
Can I use the FHSA and the Home Buyers’ Plan together?
Yes. The CRA allows HBP withdrawals and a qualifying FHSA withdrawal for the same home, as long as you meet the conditions for each.
How much is the first-time buyer land transfer tax refund in Ontario?
Ontario refunds up to $4,000. If you buy in Toronto, the city also rebates up to $4,475 of its municipal land transfer tax.
Who counts as a first-time buyer for the FHSA and HBP?
Generally, someone who has not lived in a home owned by them or their spouse or partner in the current year or the previous four calendar years. The Ontario land transfer tax refund is stricter: you must never have owned a home anywhere.
Get new detached listings first
Set up email alerts for detached homes in your price range, so you see new listings in the cities you are considering as soon as they appear.