

Detached houses carry the biggest mortgages in the GTA, so they feel interest rate moves first. On Wednesday, October 28, 2026 at 9:45 a.m. ET, the Bank of Canada is expected to raise its policy rate for the first time since 2023, from 2.25% to 2.50%. Here is the math on what that does to a detached-home budget, and why the smartest response may be at the negotiating table rather than the bank.
TL;DR
- A hike to 2.50% is the consensus call, but not a lock: 19 of 34 economists in a Reuters poll expect it.
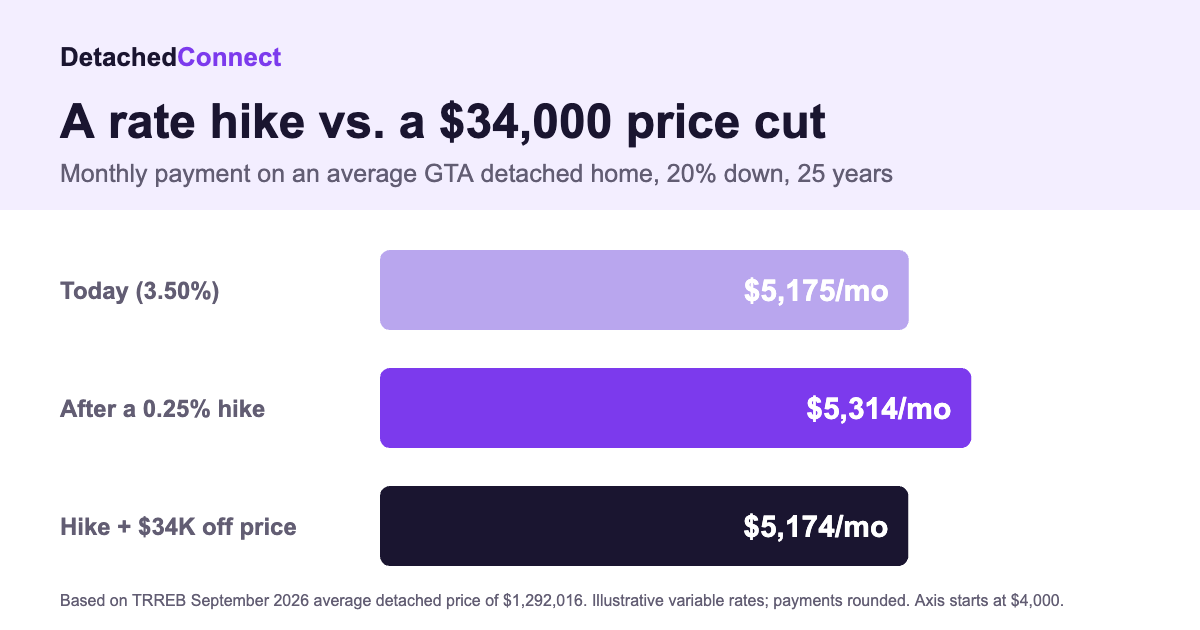
- On the average GTA detached home ($1,292,016 in September), 20% down, a quarter-point hike adds about $140 a month on a variable rate.
- Negotiating about $34,000 off the price cancels that increase completely.
- Detached sales are slower and buyers are cautious, which is exactly when price room opens up.
- Fixed-rate owners see no change until renewal.
Decision watch: The Bank of Canada announces at 9:45 a.m. ET on October 28, 2026. We will update this page with the decision and the new numbers for detached buyers shortly after.
Why this decision matters more for detached buyers
Every quarter point is charged on your whole balance, and detached buyers carry the largest balances. In September 2026 the GTA average detached price was $1,292,016, according to TRREB, compared with $907,849 for a freehold townhouse and $605,257 for a condo apartment. The same rate move costs a detached buyer roughly twice what it costs a condo buyer.
The backdrop: the Bank has held at 2.25% for seven straight decisions. Then inflation rose to 3.1% in September on higher gasoline prices, and Governor Tiff Macklem warned that the risk of inflation broadening “has gone up.” Markets priced the odds of a hike near 78% late last week. On the other side, the economy lost 68,000 jobs in September and core inflation is still under 2%, which is why TD Securities expects a hold and CIBC has suggested the Bank could wait until December.
The detached-home math, before and after
Assumptions: TRREB’s September average detached price, 20% down ($258,403), a $1,033,613 mortgage, a 25-year amortization and a discounted variable rate moving from about 3.50% to 3.75%.
| Scenario | Variable rate | Monthly payment | Change |
|---|---|---|---|
| Today | 3.50% | $5,175 | — |
| After a 0.25-point hike | 3.75% | $5,314 | +$140 a month, about $1,675 a year |
| After a hike, with $34,000 negotiated off the price | 3.75% | $5,174 | Back to where you started |
That last row is the point. A $34,000 reduction is about 2.6% of the average detached price. In a market where buyers are scarce, that is a realistic ask on many listings, and it also lowers your land transfer tax and your down payment.
The stress test is where a hike really bites
Your lender qualifies you at the higher of 5.25% or your contract rate plus 2 points. On a variable rate, a hike pushes that qualifying rate up with it. For a household whose income supports about $7,000 a month in mortgage payments:
| Qualifying rate | Approximate maximum mortgage |
|---|---|
| 5.50% (variable at 3.50%) | $1,139,900 |
| 5.75% (variable at 3.75%) | $1,112,700 |
| Difference | About $27,000 less |
If you are on the edge of qualifying for the house you want, get a pre-approval with a rate hold now. A hold locks the rate you qualify at for up to about four months, even if rates rise after Wednesday.
Tip: Detached homes under $1.5 million qualify for insured mortgages. The minimum down payment is 5% of the first $500,000 and 10% of the remainder, about $104,200 on a $1,292,016 home. Insured mortgages often carry lower rates than uninsured ones, which can offset part of a hike.
Where detached prices and demand stand
TRREB reported 2,399 detached sales across the GTA in September 2026, at an average of $1,292,016, with listings taking an average of 31 days to sell. Across all home types, sales were down 9% year over year and the average price was down 5.1%. TRREB said buyers want confidence that inflation will not keep pushing up borrowing costs. A hike, or even a clear signal of one, keeps many of them waiting.
For buyers who are ready, that is leverage. Compare what nearby detached homes actually sold for with sold prices before you offer, and use the city reports, like the Markham detached report or the Etobicoke detached report, to see how long homes sit where you are shopping.
Your detached-buyer game plan for this week
- Get pre-approved with a rate hold before the announcement if you are buying in the next four months.
- Run your numbers at 2.50% and 2.75%. Several forecasters see a second hike by early 2027. Use the detached home calculators.
- Target listings with time on market. Homes past 30 days often have the most price flexibility.
- Know the lot. Frontage and depth drive detached value more than finishes. Read lot size and frontage.
- Selling too? A buyer-cautious market rewards pricing right the first time. Start with what your detached home is worth.
See detached homes before other buyers do
Browse detached houses for sale across Ontario, with sold history on every listing, and get alerts the moment a match or a price drop hits the market.
Frequently asked questions
Is it a good time to buy a detached house if the Bank of Canada raises rates?
It can be, if you are financially ready. A quarter-point hike adds about $140 a month to an average-priced GTA detached home with 20% down, but rate worries also thin out the buyer pool. With sales down and listings sitting about a month, many buyers can negotiate a price cut that more than offsets the higher payment.
How much less house can I afford after a rate hike?
Because of the stress test, a quarter-point hike on a variable rate trims buying power by roughly 2% to 3%. If your income supports about $7,000 a month in mortgage payments, your maximum mortgage falls by about $27,000.
Can I buy a detached home with less than 20% down?
Yes, on homes priced under $1.5 million. Since December 2024 the insured mortgage cap is $1.5 million, and the minimum down payment is 5% of the first $500,000 plus 10% of the rest. On the September 2026 GTA average detached price of $1,292,016 that works out to about $104,200, plus mortgage default insurance.
When is the next Bank of Canada rate announcement?
The next decision is Wednesday, October 28, 2026 at 9:45 a.m. ET. The one after that is December 9, 2026.
General information as of October 27, 2026, not mortgage, legal or financial advice. Payment figures are estimates using illustrative rates. Confirm your numbers with a licensed mortgage professional. Sources: Bank of Canada, Statistics Canada, TRREB Market Watch (September 2026), Reuters poll (October 21 to 23, 2026), LSEG market pricing as reported October 26, 2026.